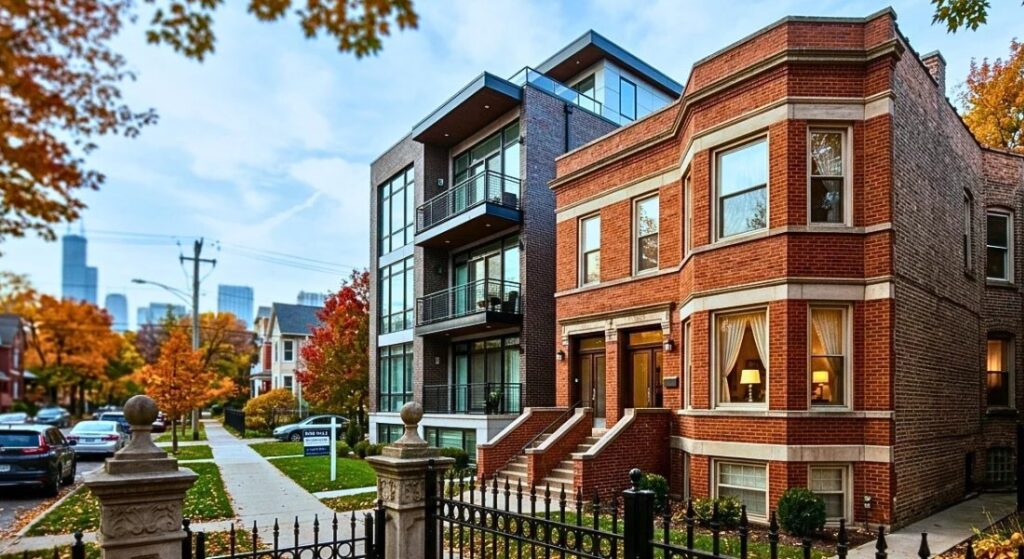
A $700,000 two-unit building in Lincoln Park offered a first-floor unit at street grade, with no steps, suited to a father with Parkinson's. It also had a spacious duplex-up for the young couple buying it. The seller was motivated and ready to accept their first offer, while comparable properties two blocks east, across an avenue, could cost 30% more.
By any reasonable measure, it was a layup. Then came the weekend and the family advice that changed everything.
Relatives may mean well when advising homebuyers, but their concerns can overshadow the specifics of a deal. Economic uncertainty, election concerns, and interest rates influenced these buyers to keep renting. Before walking away, buyers should weigh outside advice against the property's terms, their plans, and their own financial circumstances.
What Happens When the Expert Uncle Gets Involved
After reviewing the deal on Friday, the buyers spent the weekend consulting family: Mom, Dad, an uncle in California who "knows real estate". By Monday morning, the offer had fallen apart.
The concerns centered on a soft economy, rising interest rates, and election uncertainty. The family advised waiting to see how things unfolded.
Meanwhile, the buyers returned to their apartment while continuing to lose money on a condo they owned elsewhere but couldn't rent profitably.
The pattern is familiar: a buyer hesitates after hearing concerns from relatives who haven't bought or sold in years. Headlines can loom larger than the specific numbers behind a deal. The irony was that the supposedly “safe” choice may have carried greater financial risk. Those costs apparently didn't factor into the conversation with the expert uncle.
Why Family Advice Can Mislead Homebuyers
Real estate decisions feel enormous because they are enormous. That emotional weight makes people reach for reassurance from the people they trust most. The problem is that trust and expertise are not the same thing.
A parent who bought a home years ago experienced different rates, inventory dynamics, and financing options. An uncle in California faces different economic conditions, regulations, and price pressures than Chicago buyers do. The instinct to protect is genuine, but past experience may not reflect today's local market.
What gets lost in those weekend conversations is specificity. The deal wasn't about the Chicago market in the abstract. It involved a specific building, a motivated seller, and a price that appeared favorable compared with nearby properties. That context can be difficult to convey to someone unfamiliar with the current neighborhood.
Real estate decisions require a property-specific analysis. National headlines about interest rates or economic uncertainty can't determine whether a specific Lincoln Park property makes financial sense. That gap between broad market concerns and deal-specific facts is where buyer psychology can go sideways.
The Double Standard in Real Estate Advice
After more than two decades in Chicago real estate, Mario has seen how easily outside opinions can outweigh professional advice.
"I believed buyers and sellers would still listen to the professional they hired. That's not always the case. As more technology arrives, AI and otherwise, buyers and sellers seem to think they know everything. They discount our advice, whereas they would never do that to their accountant, their doctor, or their lawyer."
— Mario Greco, Founder, The MG Group
The double standard becomes clearer when you compare real estate with other professional services. Most people wouldn't replace a cardiologist's treatment plan with a relative's opinion. They would rarely overrule an attorney based solely on a parent's instinct about contract language. In real estate, though, professional advice can compete with a weekend of family opinions. Sometimes, relatives’ concerns carry more weight than an agent’s guidance.
The pattern can emerge in any market cycle. Rates and inventory still matter, but so do the emotional weight of a major purchase and the desire for reassurance from people you love.
The Psychology Behind Selling Real Estate
The conventional picture of a real estate agent is someone who shows homes and negotiates offers. That picture misses the most demanding part of the job.
"Selling real estate isn't actually selling real estate. It is psychological counseling. It is expectation leveling and selling a deal that is in the client's best interest. You would think it's a house, a price, a comp, a loan. Nope. It's still subjective."
— Mario Greco, Founder, The MG Group
The subjectivity is real, and it doesn't go away by ignoring it. The best agents surface it, name it, and walk clients through it with data. When outside opinions introduce doubt, returning to a fact-based discussion can be difficult.
The agents who do this well understand that more information doesn't always lead to better decisions. What matters is the quality and relevance of the advice.
What the Math Actually Said on the Lincoln Park Deal
Strip the emotion from the Lincoln Park deal, and the financial trade-offs become clearer.
The buyers were already paying rent while carrying a condo they couldn't rent profitably. The two-unit building offered a way to change that arrangement. The father could move into the step-free ground-floor unit, while the couple occupied the spacious duplex-up. The price also appeared favorable compared with properties two blocks east.
Instead, the weekend conversation focused on economic uncertainty, interest rates, and the election. Those concerns mattered, but they didn't answer whether this particular property suited the buyers' needs and finances.
The buyers continued renting, and the condo remained a financial burden. The opportunity to combine their housing plans in one property was gone.
Evaluating a Chicago property? Contact the MG Group team about the numbers, the terms, and the trade-offs before making a decision.
Three Moves to Protect Your Decision Before the Weekend
If you're weighing a major purchase, three steps can help you evaluate the deal before outside opinions cloud your judgment.
1. Put the numbers in writing.
Before discussing the deal with others, outline its impact on your finances. Consider housing costs, potential rental income, equity, property taxes, maintenance, and other expenses. The Cook County Assessor's Office can help you verify assessed values, but confirm actual property tax bills separately.
2. Choose your advisors carefully.
A real estate attorney, accountant, or recent buyer in the same market may offer useful perspective. Family members can provide emotional support, too. Just remember that experience from another market or decades ago may not reflect current local conditions.
3. Ask your agent to document the risks.
A good agent should explain the potential downsides, identify uncertainties, and help you weigh the trade-offs without pressuring you. For legal questions, consult a real estate attorney who can explain the protections and obligations that apply to your specific contract.
If the numbers and risks still support moving forward, you can make that decision with greater confidence. If they don't, a closer review may help you avoid a costly mistake.
The Lincoln Park deal shows what can happen when outside opinions outweigh a property's specific merits. Before walking away, make sure you understand the numbers, the risks, and the alternatives.
FAQs About Family Advice and Real Estate Deals
How can family advice derail a real estate deal in Chicago?
Family members may offer advice based on outdated market conditions or experience in another city. Their concerns can shift attention away from a property's price, condition, location, and financial implications. Buyers should weigh those opinions against current market data and the specifics of the deal.
Is it a good idea to consult family before buying a home?
Yes, especially when a family member has relevant expertise or understands your financial priorities. An accountant can review cash flow, while a real estate attorney can explain contract terms. A relative who recently bought in the same market may also offer useful perspective. Older experiences can provide context, but current local conditions deserve more weight.
How does a real estate agent's advice differ from a family member's?
An experienced local agent can provide neighborhood-specific sales data, comparable transactions, and insight into a seller's position. Family members may understand your priorities and concerns, but they may not have access to the same market information. Buyers should consider both perspectives while evaluating the property's merits and risks.
What should a buyer do when a deal feels risky?
Ask your agent to explain the potential downsides and document the key considerations. Review the property's costs, condition, financing, and fit with your plans. Consult an attorney or other qualified professional when needed. A thorough review can help you distinguish a manageable risk from a reason to walk away. For more on contract protections, read How Chicago Buyers Use Attorney Review to Compete Without Gambling Their Earnest Money.
Can waiting to buy a home cost more money?
Yes, depending on the circumstances. Rent provides housing but does not build ownership equity. Meanwhile, a property that meets your needs may sell while you're deciding. However, buying also carries costs and risks, so compare the financial implications of moving forward with those of waiting before making a decision.
How long is the Illinois real estate attorney review period?
The deadline depends on the terms of the signed contract. Many Illinois residential contracts include an attorney review provision that allows a limited period to review the agreement and propose changes. Buyers should confirm the applicable terms and deadlines with their attorney rather than assume every contract provides the same five-business-day period or cancellation rights. The Illinois State Bar Association outlines the attorney review process and the importance of legal guidance when buying a home.
How is financing a Chicago two-flat different from financing a single-family home?
Financing depends on how the property will be used, the loan program, and the borrower's qualifications. Some conventional loan programs allow buyers to finance an owner-occupied two-unit property with a lower down payment than may be required for an investment property. Eligible rental income from the second unit may also help a buyer qualify, subject to lender requirements. A mortgage professional can explain the available options and estimate the property's monthly costs.
Make the Decision With the Numbers in Front of You
The Lincoln Park deal shows how quickly a promising opportunity can slip away when outside concerns overshadow the numbers. Economic uncertainty and rising interest rates mattered, but they couldn't answer whether this particular property made sense for these buyers.
If outside opinions are making it harder to evaluate a Chicago property, connect with Mario and the MG Group. A clear review of the numbers, risks, and alternatives can help you make a more informed decision.
ABOUT THE AUTHOR
Mario Greco | Founder, The MG Group at Compass | 24+ years, 5,080+ transactions, $2B+ in career sales | #1 Large Team in Chicago (RealTrends 2024) | #2 Team in Chicago (RealTrends 2025) | Top 1% since 2002 | JD, Boston University | BS Engineering, Northwestern