Self-managed condo buildings in Chicago are facing closer lender scrutiny. Fannie Mae and Freddie Mac changed their condo review requirements in August 2026. The changes eliminated or restricted certain streamlined review options for conventional condo loans. Many condo projects may now face more detailed lender review, although exemptions remain for certain smaller projects.
Fannie Mae and Freddie Mac changed their condo review requirements in August 2026, affecting documentation for many conventional condo loans. Self-managed buildings may need to review their budgets, reserve funding, financial records, and meeting records. Projects that do not meet applicable lender requirements may face financing delays or fewer eligible financing options. Early preparation can help associations avoid documentation issues when owners decide to sell.
The 2026 Changes to Condo Project Reviews
Fannie Mae's Full Review requirements cover reserve funding, annual budgets, association records, and other project eligibility requirements. In August 2026, Fannie Mae retired its Limited Review process for applicable loan applications. Certain smaller projects can still qualify for project-review waivers under specific conditions.
For projects requiring Full Review, lenders generally look for associations allocating at least 10% of annual assessment income to replacement reserves. For applicable loan applications dated January 4, 2027, or later, that minimum increases to 15%. A qualifying reserve study may provide another way to demonstrate adequate funding when it meets the applicable requirements.
For self-managed buildings, the updated requirements may require closer attention to existing financial and association records. Informal practices that once made self-management efficient may now need additional documentation to support conventional financing.
Self-Management Meets Stricter Lender Review
Buildings that do not qualify for a project-review waiver may face more detailed documentation requirements for conventional financing. Mario Greco has more than 24 years of experience in Chicago's condo market.
Here is how Mario frames the challenge:
"There's a rare bit of 8-to-10-to-12-to-20-unit buildings that go at it as self-managed because they want to save some money on professional management. This is fine. You're saving money. But at the same time, this is what you guys need to do now. You need to have an actual budget. You need to show that 10%, and up to 15% after January 1st, is going to reserves. You do need to have a reserve study, or your buyers, unless they're putting a whole ton down or have 800-plus credit, are not going to be able to get a loan in this building."
— Mario Greco, Founder, The MG Group
A larger down payment or higher credit score does not automatically eliminate project-level requirements for a conventional loan. Some smaller associations qualify for project-review waivers under applicable guidelines. Incomplete documentation can delay closings and, in some cases, prevent buyers from securing conventional financing in a particular building.
Documentation Gaps That Can Slow Financing
Self-managed buildings that do not qualify for a project-review waiver may face additional documentation requirements. Keeping organized financial and association records can help prepare the building for lender review.
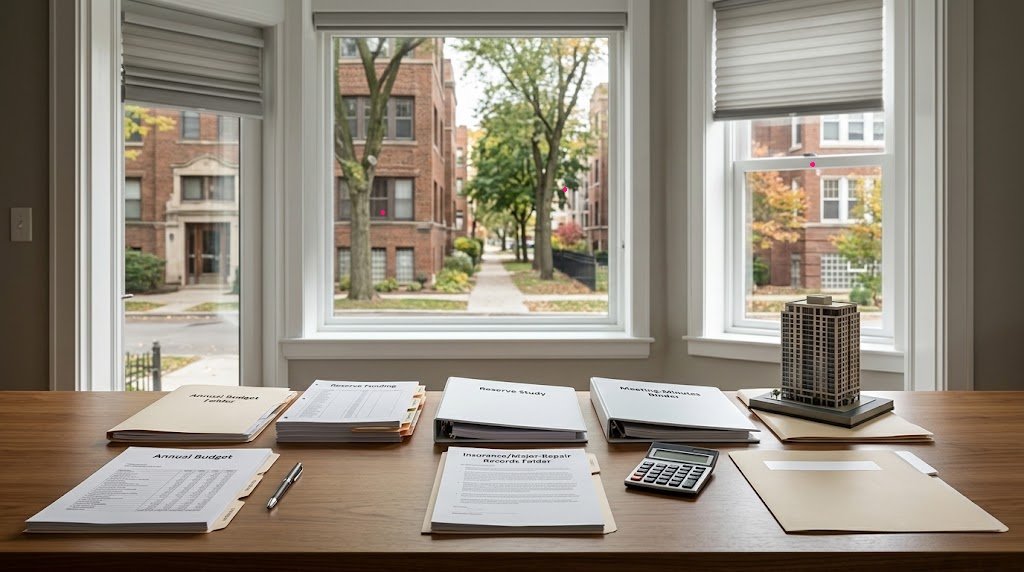
Some self-managed buildings may have gaps in their financial records and association documentation:
- No formal annual budget document.
- Reserves funded sporadically rather than systematically.
- Meeting minutes maintained only in memory or group text threads.
- A reserve study that does not meet current requirements, or no qualifying study when one is needed.
- Incomplete insurance or major repair records.
Under current Fannie Mae requirements, incomplete project documentation can lead to additional lender questions or financing delays. Sellers should also avoid assuming that a nearby transaction from six months ago followed the same review standards. A transaction that qualified under previous rules may require different documentation under updated standards.
The Financial Tradeoffs of Self-Managed Boards
Professional management adds an expense, but boards can weigh that cost against potential financing and documentation problems.
When a lender cannot approve financing because association documents are incomplete, the seller may face delays or need another buyer. The available buyer pool may also become smaller if the property cannot qualify for commonly used conventional loan programs. Multiple financing delays can create carrying costs and additional expenses for sellers and owners.
Boards can compare annual management fees with the potential costs of additional administrative work, delayed closings, and financing-related problems. The math is worth reviewing carefully rather than assuming self-management always costs less.
Not sure whether your building's documentation would hold up to a full lender review? Talk to the MG Group team before you list to review your association's documentation and prepare for potential lender requirements. An early document review can help identify areas that need attention before a buyer makes an offer.
Financing Checks Before an Offer
Updated review requirements give buyers another reason to examine a condo association's financial health before making an offer. Before committing to a unit in a smaller building, buyers should take the following steps:
- Ask whether the association is self-managed or professionally managed.
- Request the association's most recent budget and available meeting minutes.
- Confirm whether a reserve study exists and whether it meets the lender's requirements.
- Ask the lender which condo project-review requirements apply to the building.
The Illinois attorney review period also gives buyers and their attorneys an opportunity to evaluate available association documents. Reviewing those documents early can help buyers identify concerns and discuss financing options before they affect the closing.
For a detailed guide to the attorney review process, read How Chicago Buyers Use Attorney Review to Compete Without Gambling Their Earnest Money.
Self-Managed Condo Financing Questions
What is a full condo association review for a conventional loan?
A full condo project review is a lender's examination of an association's financial and operational condition before approving an eligible conventional mortgage. It can cover reserve funding, annual budgets, association records, and other project eligibility requirements. Lenders must also verify applicable insurance requirements. If a project does not meet applicable requirements, the loan may not qualify for that financing program.
Does self-management automatically disqualify a building from conventional financing?
No. Self-management itself is not a disqualifying factor because lenders evaluate the building's eligibility and applicable documentation requirements. Self-managed buildings may need formal budgets, reserve records, and written meeting minutes for lender review.
What documents should a self-managed condo association have ready for lender review?
A self-managed association should keep its current budget, financial records, meeting minutes, reserve information, and applicable insurance records organized and readily available. Lenders may also need information about significant repairs, assessments, or other project conditions when evaluating the building. Having these records prepared can help the lender identify the information needed for project review and reduce avoidable delays.
What reserve funding percentage do lenders require for Chicago condo buildings?
For projects requiring Full Review, Fannie Mae generally requires associations to allocate at least 10% of annual budgeted assessment income to replacement reserves. For applicable loan applications dated January 4, 2027, or later, that minimum increases to 15%. A qualifying reserve study may provide an alternative to the standard percentage calculation when it meets Fannie Mae's requirements. For additional details, read New Fannie Mae and Freddie Mac Rules Change Chicago Condo Buying.
What is a reserve study and how current does it need to be?
A reserve study is a professional assessment of a building's common elements and the funding needed to maintain or replace them. It may cover roofs, HVAC systems, elevators, parking structures, and other shared components. The study must meet applicable lender requirements if the lender relies on it to evaluate reserve funding. Under the updated Fannie Mae rules, the budget must reflect the study's highest recommended reserve allocation when the study is used for this purpose.
Are there lender options for buyers when a Chicago condo building doesn't qualify?
Yes. Portfolio lenders and some credit unions may offer mortgage products with different condo association review standards. Those products can have different interest rates, down payment requirements, and documentation rules. Buyers should compare available options with their lender before assuming a particular building cannot be financed.
Does the full condo review apply to two-flat and three-unit buildings in Chicago?
Fannie Mae's condo project-review requirements apply to condominium ownership structures, not ordinary two-flat or three-flat rental buildings without condominium ownership. Qualifying two- to four-unit condominium projects can receive a waiver from project review under current Fannie Mae guidelines. Basic property and project eligibility requirements still apply when project review is waived.
One Conversation Can Prevent a Dead Deal
Self-managed condo documentation is easier to address when owners prepare before a listing goes live. Current financial records give lenders the information they need to evaluate financing eligibility.
If you own a unit in a self-managed Chicago condo building, start by reviewing the association's reserve funding and financial records. Buyers considering smaller condo buildings should also review the association's financial health before writing an offer.
Working with professionals familiar with current lender review requirements can help both buyers and owners identify potential documentation issues early. Connect with Mario and the MG Group to discuss your building's documentation and financing considerations.
ABOUT THE AUTHOR
Mario Greco | Founder, The MG Group at Compass | 24+ years, 5,080+ transactions, $2B+ in career sales | #1 Large Team in Chicago (RealTrends 2024) | #2 Team in Chicago (RealTrends 2025) | Top 1% since 2002 | JD, Boston University | BS Engineering, Northwestern